28 September 2026
Open a Holding Company in Greece
If you want to register a Greek holding company, we invite you to contact our specialists for consultancy services.
Our team of consultants in company registration in Greece can provide a presentation concerning the tax system applicable to a holding and can also help investors register this entity with the local authorities. If you want to open a holding in Greece, you can rely on us for full corporate services.
What is a holding in Greece?
A holding company in Greece defines a type of business which can be incorporated for non-commercial purposes. The main characteristic of a holding company is that its primary activity is to purchase shares in other companies, with the purpose of establishing a group of entities in which the main company (the holding) has the main managerial rights.
| Quick Facts | |
|---|---|
| Legal entities used | A holding company in Greece can take the form of a limited company or a public company. |
Incorporation method | Standard registration procedure. |
Incorporation time | Around 2 weeks. |
| Types of assets owned by the holding | Real estate, financial assets, etc. |
| Requirement for local bank account (Yes/No) | Yes |
| Residency requirements for the founder(s) | There aren’t any residency requirements for the shareholders of a holding company in Greece. |
| Advantages | Tax exemptions, risk reduction for the holding, asset protection, diversification of investments, a central control. |
| Precautions | High operating costs, complexity (there are many structures, many reporting obligations for each company, complex management, etc.). |
| Shareholding structure | A company can be considered a holding when owning at least 10% of the voting rights of another company (from this threshold on, it can benefit from various tax exemptions). Many holdings own the majority of shares of a company (minimum 51%). |
| Minimum capital | EUR 25,000 for a public company, EUR 1 for a private limited company. |
| Taxation | Exemption on the taxation of dividends and the withholding tax if the holding company in Greece owns at least 10% of another company’s shares for a period of minimum 2 years. The company is liable to the payment of the corporate income tax. |
| Control | The holding exerts control on its subsidiaries (on the management of its subsidiaries). |
| Registered agent requirements | Not required. |
| Accounting and reporting | A holding must complete accounting and reporting obligations for its activities in Greece following the tax and accounting laws applicable in this country. |
| Number of double taxation treaties | 58 |
What company types can I use for a holding?
A holding company needs to be incorporated under one of the Greek business forms that have separate legal personality. In this case, it is recommended to choose one of the following company types:
- the limited liability company (EPE);
- the private company (IKE) – this represents a similar entity to EPE, only that is has simpler incorporation requirements;
- the public limited company (AE).
Which company type should I choose?
This is highly influenced by your business plans in Greece. The EPE and IKE are private companies, suitable for SMEs and which have low capital requirements, while the AE can be listed on the stock exchange and it is ideal for large companies. We recommend you address our consultants for advice on the best option for your business.
How can your team assist me in the incorporation process?
Our team of experienced consultants is specialized in offering professional services on company formation in Greece. In the list below, we will focus on the legal services our clients will obtain if they want to incorporate either of the private companies mentioned above (we will focus on these business forms as they represent popular options for starting a business here):
- company name approval;
- specific company formation assistance (obtaining the documentation from our client, drawing up the statutory documents, registering with the local authorities, etc.);
- obtaining a company seal.
How much will it cost to benefit from your company formation services?
If you will register a holding in Greece as an IKE we will charge a fee of EUR 2,400 for the legal services presented above. For registration of the EPE, we charge EUR 2,600.
Do I need to assign a registered address in Greece for my holding company?
Yes. This is a mandatory requirement that must be completed by those who open a company in Greece, regardless of its nature. Please know that our team of consultants can help you find a suitable registered address (this is a separate service we offer, outside the standard company registration package mentioned earlier). Assistance in this matter will cost EUR 950.
What is the tax regime applicable to a holding company in Greece?
Holdings are taxed following the basic taxation principles in Greece. However, they can also enjoy a special tax regime, which implies that the company can be exempted from the payment of various taxes, as long as specific requirements are met.
Are there any specific regulations for EU holdings?
Yes, in the case of a holding group that is situated in countries that are members of the European Union (EU), a holding company in Greece can benefit from the provisions of theEU Parent – Subsidiary Directive. Besides this Directive, additional regulations can also be derived from the Directive 2003/123/EC.
Below, you can watch a short video on the Greek holding:
What is the minimum shareholding requirement?
In 2006, the law required a shareholding of minimum 20% in order for theParent – Subsidiary Directive to be applied. After that, up until 2008, the shareholding requirement was reduced to 15% and since 2009, the shareholding requirement has been of only 10%.
What are the withholding taxes in Greece?
A holding company in Greece can qualify for the exemption on the payment of withholding taxes. In general, those who open a Greek company can be charged with the following rates for this type of taxes:
- 5% withholding tax on dividends;
- 15% withholding tax on interest;
- 20% withholding tax on royalties, technical projects, management fees, consultancy services.
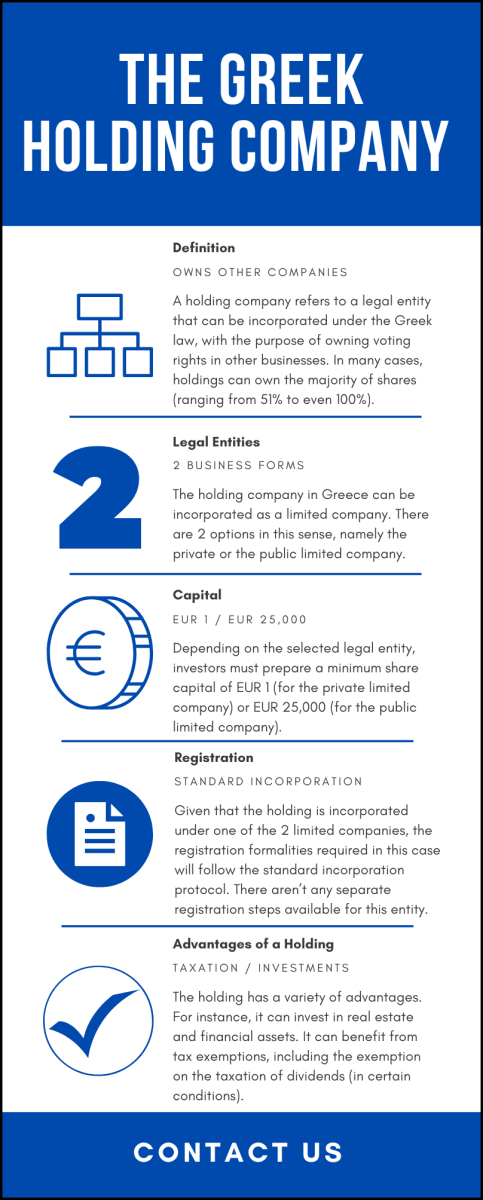
Below, we invite you to read our infographic on the Greek holding company:
When can the holding obtain an exemption on the payment of withholding tax on dividends?
Below, you can find out some information regarding the taxation system in Greece applicable to dividends:
- tax exemptions can be applied for a Greek holding company under the EU Parent – Subsidiary Directive 2011/96/EU (which replaced Directive 90/435/EEC);
- this will apply if the holding is a EU based company that holds at least 10% of the shares of Greek company;
- the 10% shareholding has to be maintained for a period of at least 2 years (consecutive years);
- if all the above conditions are satisfied, then the holding company will not be liable for the payment of the withholding tax on dividends if the same 10% shareholding is maintained for minimum 2 years;
- in the case in which the dividends are distributed, without meeting these conditions, the 5% withholding tax on dividends applies.
Please contact our specialists in company formation in Greece for further legal information on the registration of a Greek holding.