11 August 2026
Open a Joint Stock Company in Greece
You can discover here the main steps required to open a joint stock company in Greece. Please contact us for more details.
Greece provides several types of companies, the same that can be incorporated in other European countries (however, differences can appear in terms of capital, number of shareholders, residency requirements, etc.). One of these company types is the joint stock company in Greece.
Investors can open a joint stock company in Greece if they want to set up a large business, with many employees and which requires a large capital. If you need assistance in the registration process, our team of specialists in company registration in Greece remains at your service.
Establish a joint stock company in Greece – the main registration steps
In order to open a company in Greece as an A.E., investors must first gather the necessary documentation required by the local authorities. For this, a registration file must be prepared, and here, you can rely on the professional incorporation services of our team of consultants in company formation in Greece.
| Quick Facts | |
|---|---|
| Joint stock company – definition | The joint stock company is a type of legal entity that has separate legal personality than its founders, who are liable only in the amount of the contribution made. The shares of the company can be publicly traded. |
Minimum capital | In order to open a joint stock company in Greece, investors must subscribe a capital of EUR 25,000. |
Types of shareholders | Both individuals and legal entities can open a joint stock company in Greece. |
| Minimum number of shareholders | 1 |
| Types of capital contributions allowed | cash, in kind |
| Foreign ownership rules | Full foreign ownership is allowed. |
| Institution in charge with the registration of the legal entity | Commercial Registry |
| Types of systems for the administration/management of the company | Board of directors, executive committee, single-member administrative body |
| Reporting obligations | The company must prepare annual financial statements and complete audit procedures (the latter is mandatory for all joint stock companies operating as public entities). |
| Audit requirements | Statutory audit is required when the company exceeds 2 of these 3 criteria: net turnover of EUR 10 million, total assets of EUR 5 million, 50 employees (thresholds applicable from financial years starting in 2024). |
| Accounting law applicable to joint stock companies | International Financial Reporting Standards (IFRS), the Greek Generally Accepted Accounting Principles |
| Director requirements | Minimum 3 directors, or a single director (sole administrator) if the articles of association so provide |
| VAT obligations | Investors who will open a joint stock company in Greece need to register for taxation, including for VAT. |
| Censors | Not applicable in Greece |
| Residency requirements for shareholders/directors | Residency obligations appear for non-EU citizens appointed as directors. There aren’t any residency obligations for the shareholders. |
The company gains legal personality through its statutory documents – the articles of association. As per the applicable legislation, the articles of association are drawn up as a notarial deed or, if the standard articles are used, as a private document through the GEMI one-stop shop. Prior to this, our team can help you draft the documentation by including the required provisions in accordance with the commercial legislation.
The identity documents of the founders must be added to the file, as well as any immigration documents issued by the Greek authorities for foreign founders (these requirements vary based on the nationality of the investors).
An important matter to be clarified since the initiation of the process for company registration in Greece is the trading name of the legal entity, which has to be unique at a national level. The approved company name has to be registered with the Commercial Registry.
Further on, the legal entity must be registered with the same institution, which will issue a registration certificate. It is also required to obtain a Tax Identification Number and make the necessary arrangements to register the company with the Greek tax authorities.
Our team can represent investors in this procedure through the power of attorney, a service which is offered for all other stages of the registration. Our specialists will help you obtain the Greek Tax Identification Number, which is required for many online procedures completed on the platforms of the Greek institutions.
What are the characteristics of the Greek joint stock company?
The joint stock company is known as company limited by shares or, in Greek, Anonymous Eteria (A.E.). This legal entity is the most complex corporate structure that can be set up in Greece and this is why it is recommended for large businesses.
The advantage of this legal entity is that, just like in the case of the limited liability company, the investors benefit from limited liability against corporate debts. However, this company type requires a large capital deposit. Some of its main characteristics are presented below:
- investors can open a company in Greece as an A.E. if they can subscribe a minimum share capital of EUR 25,000;
- this company can be founded by 1 shareholder (who can be an individual or another company);
- for the management of the company, it is necessary to appoint a board of directors, which must be comprised of minimum 3 members (unless the articles provide for a single administrator);
- the company must obtain a VAT number, which is comprised of the country code “EL”, followed by 9 digits.
Below, you can watch a short video on the Greek joint stock company:
Why should investors opt for a joint stock company in Greece?
The registration of Greek joint stock company is recommended when investors plan to open a Greek company that will have complex operations and numerous employees. However, there are other reasons for which investors may want to opt for this entity.
For instance, the company’s shares are negotiable instruments, a right that is not granted when registering other entities. From a financial perspective, this company type can use bond loans as a way to finance itself. It must be noted that in certain industries, the law requires investors, local and foreign alike, to open a joint stock company in Greece.
The obligation appears as this is the sole structure that can be incorporated for specific activities, such as in the case of banking or insurance. Provided that investors want their company to be listed on the stock exchange, the joint stock company is the sole option as well.
What taxes can a Greek joint stock company be liable for?
Considering that the Greek joint stock company is incorporated for the purpose of developing commercial activities, it will also be liable to taxation in accordance with the applicable law. Commercial companies are required to pay the corporate tax, the VAT, charged at a rate of 24%, etc.
Tax obligations arise from the employment of local or foreign workforce and from the withholding tax charged to specific types of income and payments. In the list below, we present the standard withholding taxes:
- 5% – the withholding tax on dividends;
- 15% – the withholding tax on interest;
- 20% – the withholding tax on royalties, management fees, consultancy services, etc.
It must be noted that companies incorporated in Greece do not pay withholding taxes on royalties or on the fees charged for the provision of consultancy services, etc., therefore, those setting up a company in Greece will be exempt from this tax.
Exemption on the payment of withholding taxes can apply to foreign companies which have a permanent establishment in Greece; our consultants can explain in what situations this rule applies and for what types of services and payments.
Please know that the rates presented above can vary based on the tax residency of the shareholder (company/individual), in accordance with the stipulations of the double tax treaties signed by Greece. For instance, the withholding tax on dividends can apply at other rates, such as 0% under the EU Parent-Subsidiary Directive; treaty rates above the 5% domestic rate do not apply, as a treaty cannot increase the domestic tax.
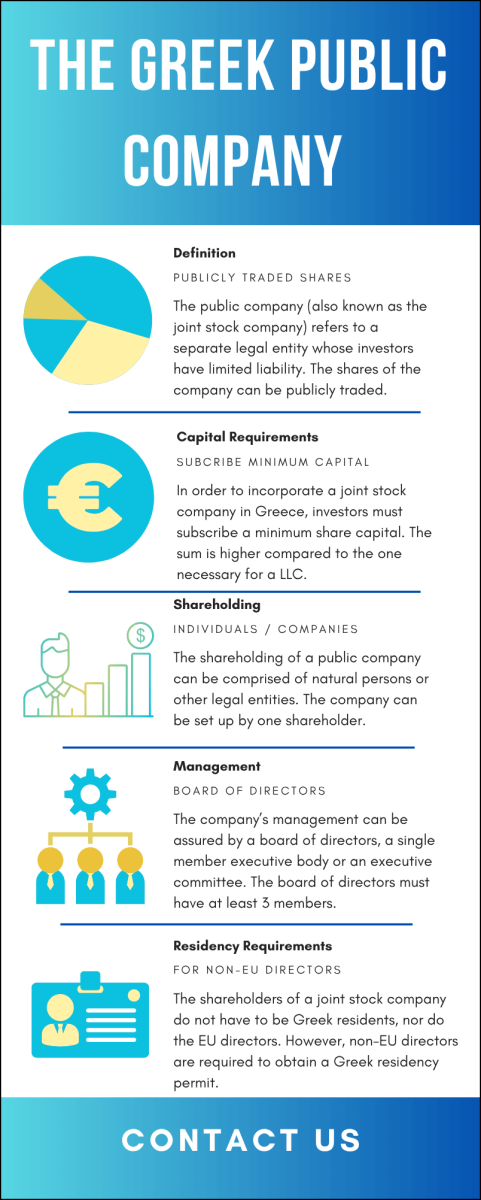
We advise you address our consultants in Greek company formation for tax advice concerning the manner in which the provisions of these agreements apply. The infographic below offers concise information on the Greek public company:
Can a foreign joint stock company operate in Greece without permanent establishment?
A permanent establishment refers, from a legal point of view, to the actual place of business where the company develops its activities (the registered address). The permanent establishment also refers to the location in Greece where the respective legal entity operates.
The legislation in Greece, which implements the EU’s laws, allows foreign companies to carry out business activities in this country without having a permanent establishment (this means that the foreign entity does not go through all the steps for company formation in Greece).
Still, a set of legal procedures need to be completed with the Greek authorities, including for tax purposes. One of the first basic requirements is to apply for a Tax Registration Number issued by the Greek tax administration.
Please mind that this is a mandatory legal procedure for all foreign legal entities engaging in economic activities in Greece, as per the rules of the Code of Tax Procedure (Law 4987/2022, which codified and replaced Law 4174/2013). Another obligation imposed to such foreign companies is to contact the tax administration and submit a declaration of commencement of business activity.
This procedure must be completed in maximum 30 days since the day in which the company registered its incorporation documents (issued by the authorities of the foreign country where the company was initially registered) with the Greek authorities.
The registration of the incorporation papers is generally completed through the General Electronic Commercial Registry, by following the basic protocol (our consultants in company registration in Greece can handle the entire procedure on behalf of foreign clients).
As mentioned above, the foreign company must apply for a tax registration number in Greece provided that it conducts taxable activities in Greece. Foreign companies established within the EU, which conduct taxable activities without permanent establishment in Greece, must abide by the rules of the following laws:
- Decision Circular 1153/2016, Articles 1-3;
- Decision Circular 1089/2015;
- Ministerial Decision Circular 1113/2013, Articles 1-4 (on matters such as the assignment of tax identification numbers, submission of VAT returns, payment of VAT);
- the VAT Code, Law 5144/2024, which replaced Law 2859/2000 (taxable entities established within the EU states that do not have an establishment in Greece).
Our specialists in Greek company formation can present any other obligations that may appear from cross-border activities of companies established within the EU area.
We invite you to contact our consultants if you want to set up a joint stock company in Greece, a legal entity that is set up in accordance with the Law 4548/2018. We can also provide legal representation during the setup of a corporate bank account, another mandatory procedure during the incorporation process.